Force Placed Insurance Charges Allow Special Defense to Foreclosure
Read the full article at https://lnkd.in/dZSesj2Q, see the full video at https://lnkd.in/dCYDuKxw and at https://lnkd.in/dUbx5bf8 and at https://zalma.com/blog plus more than 4800 posts.
Post 4802
In an action to foreclose a mortgage the trial court granted in part the plaintiff’s motion to strike the defendant’s special defenses and counterclaim; subsequently, the court, Cirello, J., granted the plaintiff’s motion for summary judgment as to liability only; thereafter, the court, Spader, J., rendered judgment of foreclosure by sale, and the defendant appealed.
In M&T Bank v. Robert R. Lewis, No. SC 20817, Supreme Court of Connecticut (April 30, 2024) the appeal of a foreclosure judgment presented one question important to insurance professionals: Whether allegations of impropriety in a mortgagee’s force placement of property insurance arise from the making, validity or enforcement of the mortgage for purposes of a special defense to a foreclosure action.
FACTS
Robert R. Lewis claimed that the trial court improperly granted the plaintiff’s motion to strike two of the defendant’s special defenses arising from the plaintiff’s conduct in its force placement of flood insurance on the property at issue, alleging that the plaintiff had unclean hands and breached the implied covenant of good faith and fair dealing on the ground that those defenses do not arise from the making, validity or enforcement of the mortgage.
After the defendant failed to make his monthly payment on August 1, 2017, the plaintiff notified him in writing of his default. The plaintiff subsequently elected to accelerate the note and foreclose on the mortgage. The parties participated in the state’s court-supervised foreclosure mediation program but were unable to reach an agreement to modify the loan.
The trial court granted the plaintiff’s motion for summary judgment as to liability only.
DISCUSSION
Defendant’s claim that the trial court improperly granted in part the plaintiff’s motion to strike the defendant’s special defenses of unclean hands and breach of the implied covenant of good faith and fair dealing predicated on the plaintiff’s improprieties in the force placement of the flood insurance, do not ”arise from the making, validity or enforcement” of the mortgage.
In the present case, the trial court struck the special defenses of unclean hands and breach of the implied covenant of good faith and fair dealing on the ground that the defendant’s allegations did not relate to ”the specific mortgage at issue in this case.” (Emphasis added.)
The question remains whether those allegations are sufficiently related to the making, validity or enforcement of the mortgage. The Supreme Court concluded that they are. The defendant alleges, the plaintiff charged the defendant an amount greater than the ”cost” of the insurance, in violation of section 5 of the mortgage agreement, concealed a ”kickback” agreement that it had with ASIC. All of this alleged conduct is directly related to the plaintiff’s reliance on and enforcement of section 5 of the mortgage agreement.
The Supreme Court noted that the alleged effect of the plaintiff’s conduct in enforcing section 5 of the mortgage agreement-that it wrongfully increased the defendant’s overall debt-provides a sufficient nexus to the foreclosure action. Defendant’s allegations in support of the special defenses are sufficiently connected to the enforcement of the mortgage.
Since an action to foreclose a mortgage is an equitable proceeding it is a fundamental principle of equity jurisprudence that for a plaintiff to show that he is entitled to the benefit of equity he must establish that he comes into court with clean hands. The clean hands doctrine is applied not for the protection of the parties but for the protection of the court. It is applied not by way of punishment but on the basis of considerations that make for the advancement of right and justice. A mortgagor who has defaulted on a mortgage is not precluded from asserting the special defense of unclean hands. Therefore, the Supreme Court took the Defendants allegations as true it concluded that the defendant alleged willful conduct that is not equitable, fair or honest.
The defendant sufficiently pleaded that the plaintiff’s alleged misrepresentations interfered with his right to receive the benefits of the agreement. This Defendant did by alleging that the plaintiff’s kickback scheme wrongfully resulted in the defendant’s payment of more than he was obligated to pay and more than the plaintiff was entitled to charge him, pursuant to the mortgage agreement.
By alleging that Plaintiff’s conduct with force placed insurance increased his overall debt the trial court improperly struck the special defenses.
ZALMA OPINION
Insurance is important to every mortgagee needing it to protect the security for the loan. Mortgages require insureds to obtain insurance and allow, if they fail, to obtain force placed insurance that only protects the mortgagee at the expense of the insured. However, the mortgagee should never charge the insured more than it pays since that would be fraudulent and, as in this case, a defense to the foreclosure.
(c) 2024 Barry Zalma & ClaimSchool, Inc.
Please tell your friends and colleagues about this blog and the videos and let them subscribe to the blog and the videos.
Subscribe to my substack at https://barryzalma.substack.com/subscribe
Go to X @bzalma; Go to Newsbreak.com https://www.newsbreak.com/@c/1653419?s=01; Go to Barry Zalma videos at Rumble.com at https://rumble.com/c/c-262921; Go to Barry Zalma on YouTube- https://www.youtube.com/channel/UCysiZklEtxZsSF9DfC0Expg.
Go to the Insurance Claims Library – https://lnkd.in/gwEYk.
Go to Rumble.com at https://lnkd.in/gV9QJYH; and https://lnkd.in/g2hGv88.
Subscribe to my substack at https://lnkd.in/gmmzUVBy; Go to X @bzalma.

Insurance Expert May Not Testify to Speculative and Contains Unsupported Conclusions.
Posted on September 18, 2026 by Barry Zalma
See the full video at and at https://rumble.com/v7fmifw-expert-may-only-testify-to-what-experience-supports.html
In Michele A. Over, and The Estate Of Paul R. Over v. State Farm Mutual Automobile Insurance Company, and State Farm Fire And Casualty Company, Civil Action No. 23-cv-02243-PAB-STV, United States District Court, D. Colorado (September 14, 2026) Michele and Paul Over sued State Farm Fire and State Farm Auto over hail-damage and stolen-vehicle claims.
The operative dispute concerned State Farm Auto’s motion to exclude or limit opinions from plaintiffs’ insurance-industry expert, Aaron Castillo. Castillo.
Law
The proponent of expert testimony must establish by a preponderance of the evidence that an expert is qualified and that the opinions are helpful, sufficiently grounded, and reliably derived and applied. Experience-based opinions must explain how the...
150 Months in Prison for Tax Fraud
Post 4846
Posted on September 17, 2026 by Barry Zalma
See the full video at https://lnkd.in/g8rh3JBX and https://lnkd.in/gmkdy-9C, In United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
In United States Of America v. Thomas Addaquay, United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
Thomas Addaquay controlled United Consolidated Accounting and Business Services (UC), nominally a check-cashing business.
The government proved a three-stage tax-refund scheme that converted the resulting refund checks into usable funds through ...
Major Fraud Perpetrator Asserts Fifth Amendment Privilege to Avoid Prosecution
Post 5489
Posted on September 14, 2026 by Barry Zalma
Fraudster Refuses to Answer Questions About His Alleged Fraud
See the full video at https://lnkd.in/gvicAMDr and at https://lnkd.in/gvicAMDr
In Great American Insurance Co. v. Gemstone Property Management, LLC, et al., No. 23-cv-9100 (LJL), United States District Court, S.D. New York (September 8, 2026) Great American Insurance Company alleged that it was defrauded through a scheme in which Subin Associates, LLP recruited individuals to stage construction-site injuries, arranged unnecessary medical treatment and litigation funding, and pursued fraudulent personal-injury claims.
Luis Manuel Garcia Salcedo, resulted in a $6 million settlement. Non-party Jose Hernandez allegedly worked as an assistant manager at Subin, operated Hernandez Associates, and owned litigation-funding companies that shared office space with Subin and provided services to its clients.
After Great American ...
Post 4582
Posted on November 17, 2026 by Barry Zalma
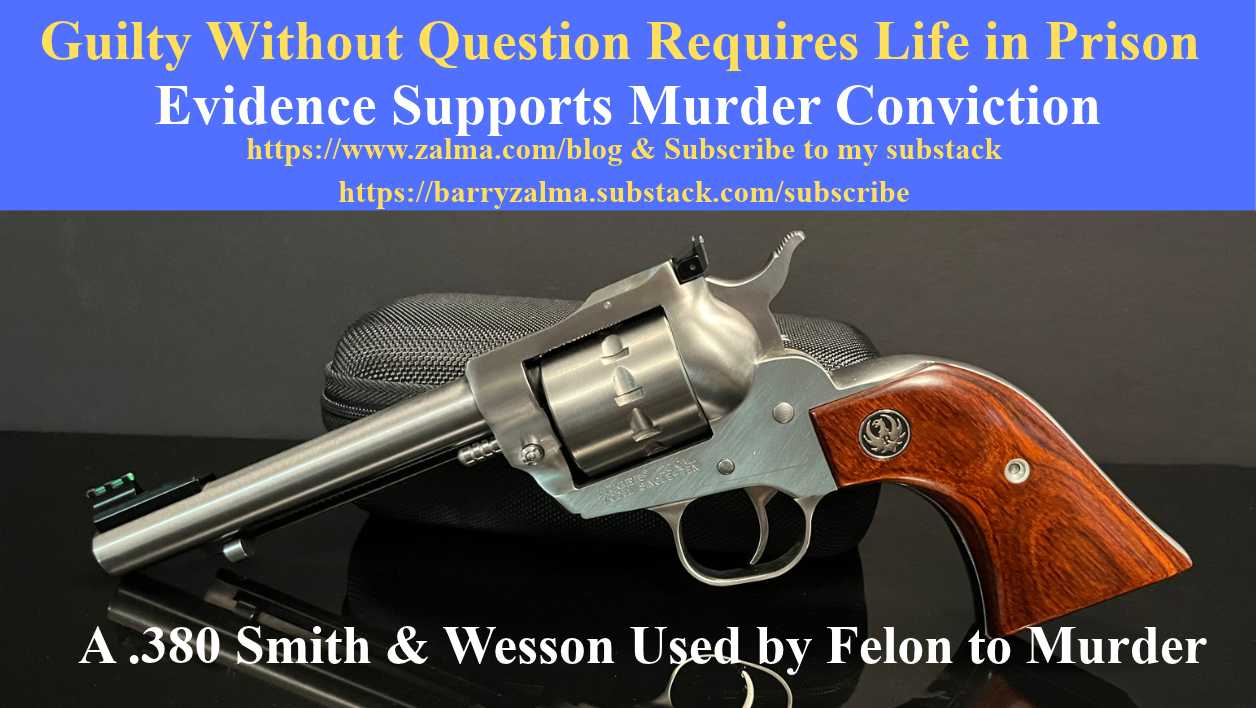
Evidence Supports Murder ConvictionA .380 Smith & Wesson Used by Felon to Murder
In State Of Louisiana v. Curtis Joseph Thomas III, No. 25-KA-612, Court of Appeals of Louisiana, Fifth Circuit (November 4, 2026) the court noted that On Feb. 13, 2022, Thomas called 9-1-1 for an ambulance for a shooting victim at 645 Emile Avenue in Westwego. This was a known “trap house” where drugs were bought, sold and used.
Deputy Vasquez found Thomas walking away from the scene. He searched him and recovered a .380 Smith & Wesson pistol from his pocket. Charles McGehee was killed by two gunshot wounds.
Tyran Simpson was shot in the arm. Simpson identified Thomas as the shooter. The lights and TV went out, and he saw “flames from a gun” from the door where Thomas stood. Simpson admitted he was armed that night and had several prior convictions.
EXPERT TESTIMONY
The firearm examiner matched the casings and both projectiles from McGehee’s body to the pistol found on Thomas.
The DNA expert...
THE SOURCE FOR THE INSURANCE FRAUD PROFESSIONAL
ZIFL Volume 30, Issue 22
November 15, 2026
Zalma’s Insurance Fraud Letter (ZIFL) continues its 30th year of publication dedicated to those involved in reducing the effect of insurance fraud. ZIFL is published 24 times a year by ClaimSchool and is written by Barry Zalma. It is provided FREE to anyone who visits the site at http://zalma.com/zalmas-insurance-fraud-letter-2/
Zalma’s Insurance Fraud Letter (ZIFL) continues its 30th year of publication dedicated to those involved in reducing the effect of insurance fraud. ZIFL is published 24 times a year by ClaimSchool and is written by Barry Zalma. It is provided FREE to anyone who visits the site at http://zalma.com/zalmas-insurance-fraud-letter-2/
Convicted of...
Claims of Res Judicata and Procedural Default Defeats Habeas
Post 5543
Posted on November 13, 2026 by Barry Zalma
A Health Insurance Fraud Conviction Rested On Knowingly Submitting Materially False Or Misleading Claim Information With Specific Intent To Defraud.
A Health Insurance Fraud Conviction Rested On Knowingly Submitting Materially False Or Misleading Claim Information With Specific Intent To Defraud.
In Tariq Mustafa Abdulaziz v. Commissioner Of Correction, No. CV 26-5002432-S, Superior Court of Connecticut, Judicial District of Tolland, Habeas Docket (October 29, 2026) Tariq Mustafa Abdulaziz submitted 114 claims for in-home, face-to-face services purportedly provided to thirty program participants during four one-week periods. The department paid Neurostrategies, Inc., $13,650.
FACTS
The defendant waived his right to a jury trial and elected a trial to the court, D'Addabbo, J. Trial occurred over the course of eight days in August, 2022. The state presented testimony from ten witnesses and introduced thirty-three exhibits into ...