Claims Commandment III: Thou Shall Communicate Often With The Third Party Insured and the Claimant
Barry Zalma
Read the full article at https://www.linkedin.com/pulse/claims-commandments-barry-zalma-esq-cfe-1c and see the full video at https://rumble.com/v1qrtao-claims-commandments.html and at at https://zalma.com/blog plus more than 4350 posts.
Insurance claims is a service business. The claims person – whether acting for the insurer or the insured – provides a service to the insured and the insurer. Communication is essential to providing the service promised by the insurance policy.
In some states, like California, communications are required by regulation:
"Every insurer shall disclose to a first party claimant or beneficiary, all benefits, coverage, time limits or other provisions of any insurance policy issued by that insurer that may apply to the claim presented by the claimant. When additional benefits might reasonably be payable under an insured’s policy upon receipt of additional proofs of claim, the insurer shall immediately communicate this fact to the insured and cooperate with and assist the insured in determining the extent of the insurer’s additional liability." [10 CCR 2695.4 (a)]
This means that the initial written contact with an insured in a first party property claim should advise the insured of all benefits, coverage, time limits, or other provisions of any insurance policy issued by that insurer that may apply to the claim presented by a first party insured.
When a claims person receives any communication from an insured, third party claimant, or a representative of the insured or claimant regarding a claim that reasonably suggests that a response is expected, he or she should immediately after receipt of that communication furnish the claimant with a complete response based on the facts as then known by the claims person. Some regulations allow the claims person up to 20 days to respond. Good claims handling requires an immediate response. If the response is oral rather than written it should be noted in the claims person’s file or log.
Upon receiving notice of claim, every insurance claims person should immediately do the following:
Acknowledge receipt of such notice to the claimant or insured.
If the acknowledgment is not in writing, a notation of acknowledgment must be made in the insurer’s claim file and dated.
Provide to the claimant or insured necessary forms, instructions, and reasonable assistance, including but not limited to, specifying the information the claimant must provide for proof of claim;
Begin any necessary investigation of the claim.
The investigation must be “real.” The claims person or investigator must actually contact the insured, the claimant, the witnesses and start collecting the documents needed to complete the claims investigation. Investigation and must be started immediately after receiving notice of claim.
Merely reading a policy wording and notice of claim is not the beginning of an investigation or an investigation at all.
Upon receiving proof of claim, every insurance claims person should immediately accept or deny the claim, in whole or in part. Proof of claim is not the proof of loss required as a condition of the policy. A proof of claim is where the insured provides the insurer sufficient information to allow the insurer to determine part or all of the insured’s claim. The amounts accepted or denied shall be clearly documented in the claim file unless the claim has been denied in its entirety.
Some states allow up to 40 calendar days to respond to a proof of claim. If more time is required to determine whether a claim should be accepted and/or denied in whole or in part, the claims person should provide the claimant or insured written notice of the need for additional time.
The written notice should specify any additional information the insurance claims person requires in order to decide. The written notice should state any continuing reasons for the insurer’s inability to decide. Thereafter, the written notice concerning additional time to complete an investigation, should be provided to the insured at least every thirty calendar days until a determination is made.
If the determination cannot be made until some future event occurs, then the claims person should comply with this continuing notice requirement by advising the claimant and/or insured of the situation and providing an estimate as to when the determination can be made.
Effective diary systems are essential to professional claims handling or the Regulations will be violated with regularity.
Every claims person must conduct and diligently pursue a thorough, fair and objective investigation and should not persist in seeking information not reasonably required for or material to the resolution of a claim dispute.
The claims person’s obligation is not limited to communication with the insured or the claimant.
In addition, the claims person and the insurer have an obligation to communicate with the state, police agencies, or prosecutors if they suspect that an insured or a claimant is attempting fraud.
In California, and most states, such a communication is absolutely immune from suit. Pursuant to section California Civil Code Section 47(b), a privilege is stated that bars a civil action for damages for communications made “[i]n any (1) legislative proceeding, (2) judicial proceeding, (3) in any other official proceeding authorized by law, or (4) in the initiation or course of any other proceeding authorized by law and reviewable pursuant to [statutes governing writs of mandate],” with certain statutory exceptions.
The privilege established by this subdivision often is referred to as an “absolute” privilege, and it bars all tort causes of action except a claim for malicious prosecution. “The absolute privilege in section 47 represents a value judgment that facilitating the “utmost freedom of communication between citizens and public authorities whose responsibility is to investigate and remedy wrongdoing” is more important than the “‘occasional harm that might befall a defamed individual.’” (See Imig v. Ferrar (1977) 70 Cal. App. 3d 48, 55-56 [138 Cal. Rptr. 540].)”
To fulfill Commandment III the claims person must communicate promptly and often with the insured, the claimant and the insured (if a third party claim) and counsel for each. In doing so the claims person establishes a rapport with the insured and/or claimant and will make resolution of the claim easier.
No claims person should ever misrepresent or conceal benefits, coverages, time limits or other provisions of the policy from the insured or the claimant.
(c) 2022 Barry Zalma & ClaimSchool, Inc.
Barry Zalma, Esq., CFE, now limits his practice to service as an insurance consultant specializing in insurance coverage, insurance claims handling, insurance bad faith and insurance fraud almost equally for insurers and policyholders. He practiced law in California for more than 44 years as an insurance coverage and claims handling lawyer and more than 54 years in the insurance business. He is available at http://www.zalma.com and [email protected] and receive videos limited to subscribers of Excellence in Claims Handling at locals.com https://zalmaoninsurance.locals.com/subscribe.Subscribe to Excellence in Claims Handling at https://barryzalma.substack.com/welcome.
Write to Mr. Zalma at [email protected]; http://www.zalma.com; http://zalma.com/blog; daily articles are published at
Zalma on Insurance
Insurance, insurance claims, insurance law, and insurance fraud .
By Barry Zalma
Go to the podcast Zalma On Insurance at https://anchor.fm/barry-zalma; Follow Mr. Zalma on Twitter at https://twitter.com/bzalma; Go to Barry Zalma videos at Rumble.com at https://rumble.com/c/c-262921; Go to Barry Zalma on YouTube- https://www.youtube.com/channel/UCysiZklEtxZsSF9DfC0Expg; Go to the Insurance Claims Library – https://zalma.com/blog/insurance-claims-library

Insurance Expert May Not Testify to Speculative and Contains Unsupported Conclusions.
Posted on September 18, 2026 by Barry Zalma
See the full video at and at https://rumble.com/v7fmifw-expert-may-only-testify-to-what-experience-supports.html
In Michele A. Over, and The Estate Of Paul R. Over v. State Farm Mutual Automobile Insurance Company, and State Farm Fire And Casualty Company, Civil Action No. 23-cv-02243-PAB-STV, United States District Court, D. Colorado (September 14, 2026) Michele and Paul Over sued State Farm Fire and State Farm Auto over hail-damage and stolen-vehicle claims.
The operative dispute concerned State Farm Auto’s motion to exclude or limit opinions from plaintiffs’ insurance-industry expert, Aaron Castillo. Castillo.
Law
The proponent of expert testimony must establish by a preponderance of the evidence that an expert is qualified and that the opinions are helpful, sufficiently grounded, and reliably derived and applied. Experience-based opinions must explain how the...
150 Months in Prison for Tax Fraud
Post 4846
Posted on September 17, 2026 by Barry Zalma
See the full video at https://lnkd.in/g8rh3JBX and https://lnkd.in/gmkdy-9C, In United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
In United States Of America v. Thomas Addaquay, United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
Thomas Addaquay controlled United Consolidated Accounting and Business Services (UC), nominally a check-cashing business.
The government proved a three-stage tax-refund scheme that converted the resulting refund checks into usable funds through ...
Major Fraud Perpetrator Asserts Fifth Amendment Privilege to Avoid Prosecution
Post 5489
Posted on September 14, 2026 by Barry Zalma
Fraudster Refuses to Answer Questions About His Alleged Fraud
See the full video at https://lnkd.in/gvicAMDr and at https://lnkd.in/gvicAMDr
In Great American Insurance Co. v. Gemstone Property Management, LLC, et al., No. 23-cv-9100 (LJL), United States District Court, S.D. New York (September 8, 2026) Great American Insurance Company alleged that it was defrauded through a scheme in which Subin Associates, LLP recruited individuals to stage construction-site injuries, arranged unnecessary medical treatment and litigation funding, and pursued fraudulent personal-injury claims.
Luis Manuel Garcia Salcedo, resulted in a $6 million settlement. Non-party Jose Hernandez allegedly worked as an assistant manager at Subin, operated Hernandez Associates, and owned litigation-funding companies that shared office space with Subin and provided services to its clients.
After Great American ...
Insured’s Failure to Report Claim Before Expiration Defeats Claim
Post 4582
Posted on November 18, 2026 by Barry Zalma
In Diversified Restaurant Group, LLC, et al v. Houston Casualty Company, et al., No. 25-cv-02344-EMC, United States District Court, N.D. California (October 7, 2026) Diversified Restaurant Group and Golden Gate Bell (the “Insureds”) own or operate restaurants, including a Taco Bell in Antioch, California. Houston Casualty Company (HCC) issued them identical “claims made and reported” Employment Practices Liability (EPL) policies for 2022 and 2023. The 2022 policy ran from January 1, 2022 to January 1, 2023.
For the policy to apply, a covered claim had to be made during the policy period and reported to HCC within 30 days after it ended, which here was January 30, 2023. On about December 10, 2022, an underage employee reported alleged sexual misconduct.
On December 14, 2022, the employee’s counsel (Wilshire Law Firm) sent a letter to the Taco Bell. The letter referred to an “accident” on a stated date at a...
Post 4582
Posted on November 17, 2026 by Barry Zalma
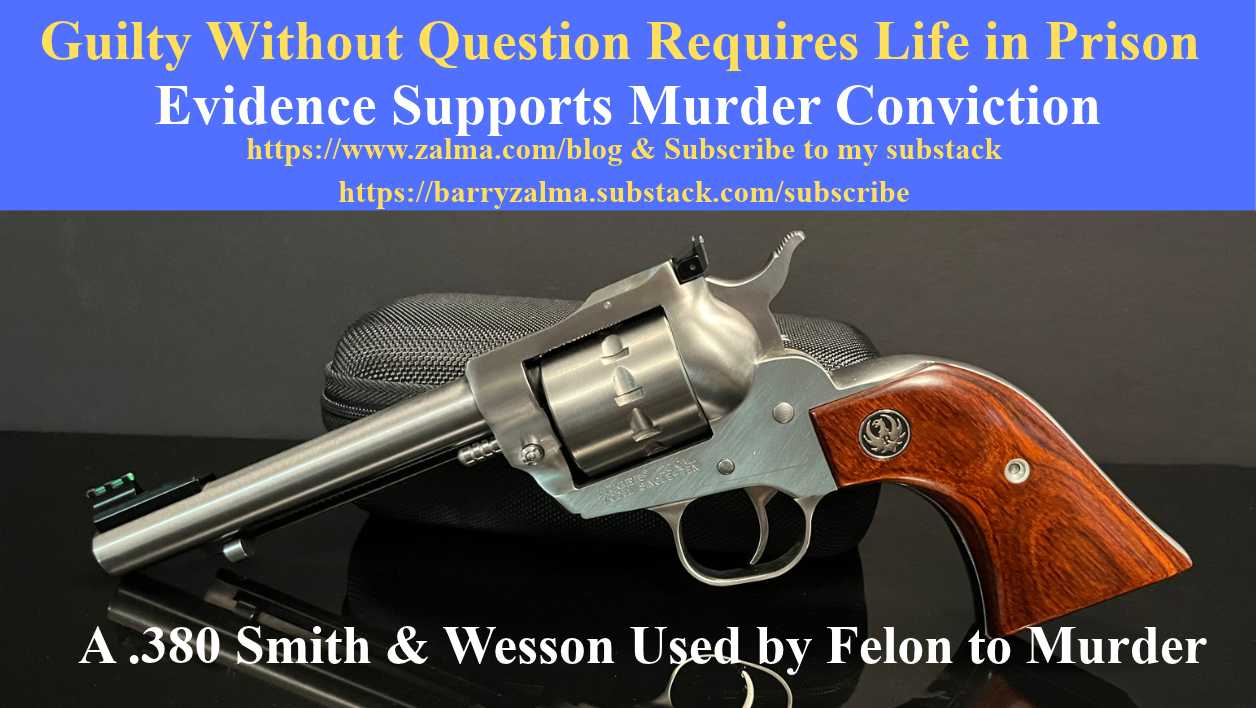
Evidence Supports Murder ConvictionA .380 Smith & Wesson Used by Felon to Murder
In State Of Louisiana v. Curtis Joseph Thomas III, No. 25-KA-612, Court of Appeals of Louisiana, Fifth Circuit (November 4, 2026) the court noted that On Feb. 13, 2022, Thomas called 9-1-1 for an ambulance for a shooting victim at 645 Emile Avenue in Westwego. This was a known “trap house” where drugs were bought, sold and used.
Deputy Vasquez found Thomas walking away from the scene. He searched him and recovered a .380 Smith & Wesson pistol from his pocket. Charles McGehee was killed by two gunshot wounds.
Tyran Simpson was shot in the arm. Simpson identified Thomas as the shooter. The lights and TV went out, and he saw “flames from a gun” from the door where Thomas stood. Simpson admitted he was armed that night and had several prior convictions.
EXPERT TESTIMONY
The firearm examiner matched the casings and both projectiles from McGehee’s body to the pistol found on Thomas.
The DNA expert...
THE SOURCE FOR THE INSURANCE FRAUD PROFESSIONAL
ZIFL Volume 30, Issue 22
November 15, 2026
Zalma’s Insurance Fraud Letter (ZIFL) continues its 30th year of publication dedicated to those involved in reducing the effect of insurance fraud. ZIFL is published 24 times a year by ClaimSchool and is written by Barry Zalma. It is provided FREE to anyone who visits the site at http://zalma.com/zalmas-insurance-fraud-letter-2/
Zalma’s Insurance Fraud Letter (ZIFL) continues its 30th year of publication dedicated to those involved in reducing the effect of insurance fraud. ZIFL is published 24 times a year by ClaimSchool and is written by Barry Zalma. It is provided FREE to anyone who visits the site at http://zalma.com/zalmas-insurance-fraud-letter-2/
Convicted of...