
Even Clear Language in Policy Can be Ambiguous
Barry Zalma
Jun 27, 2023
Read the full article at https://lnkd.in/dkKWyn5n and see the full video at https://lnkd.in/dGKNbQ_Q and at https://lnkd.in/dkp9BSwN and at https://zalma.com/blog plus more than 4550 posts.
AI Collection of Facial Recognition Images Violates Illinois Statute
After Wynndalco Enterprises, LLC was sued in two putative class actions for violating the Illinois Biometric Information Privacy Act (“BIPA”) its business liability insurer, Citizens Insurance Company of America sued seeking a declaration that it has no obligation under the terms of the insurance contract to indemnify Wynndalco for the BIPA violations or to supply Wynndalco with a defense. The district court entered judgment on the pleadings for Wynndalco, finding that the language of the catch-all exclusion is ambiguous on its face and that, construing that ambiguity in favor of the insured, Citizens consequently had a duty to defend Wynndalco.
In Citizens Insurance Company of America v. Wynndalco Enterprises, LLC, et al., No. 22-2313, United States Court of Appeals, Seventh Circuit (June 15, 2023) the litigation arose from a massive database of facial-image scans assembled by Clearview AI, an artificial intelligence firm that specializes in facial recognition software.
Clearview AI allegedly extracted in excess of three billion photographs of individuals from online social media; converted those images into biometric facial recognition identifiers using proprietary algorithms; collected the original images and their biometric counterparts into its database; and paired those images with information as to where those images were found on the Internet. Clearview AI has also created a facial recognition application or “app” that allows a user to identify an individual by uploading a photograph of that person to the app. The app then allows the user to see other photographs of that same person on the media platforms or websites where they appear, along with the identifying information (including their name, address, and other personal information) associated with that individual.
Both suits allege that Wynndalco’s role in this transaction ran afoul of BIPA. Illinois became the first state in the nation to enact biometric data privacy legislation when it promulgated BIPA. Broadly speaking, BIPA codifies an individual’s right of privacy in and control over his or her biometric identifiers and biometric information.
At the time of the sale of the Clearview AI app to the Chicago Police Department, Wynndalco had business owner’s insurance coverage through a policy issued to it by Citizens. Section II of the policy sets forth the liability coverage for the business. Citizens contends that coverage of the class action claims is barred by a catch-all provision in a policy exclusion barring coverage for injuries arising out of certain statutory violations. The catch-all exclusion provided: “Any other laws, statutes, ordinances, or regulations, that address, prohibit or limit the printing, dissemination, disposal, collecting, recording, sending, transmitting, communicating or distribution of material or information.”
Illinois regards the proper interpretation of an insurance policy as a question of law. Policy terms that purport to limit the insurance company’s liability are construed in favor of coverage, but only when the terms are ambiguous or susceptible to more than one reasonable interpretation.
In some instances, the language of a policy exclusion may appear clear in isolation, but when compared with a separate policy provision granting coverage for the same type of action or injury that the exclusion ostensibly reaches, an ambiguity arises, in that the exclusion appears to take away with one hand coverage that the policy purports to give with the other. Because the aim of policy interpretation is to give effect to all provisions of the policy and avoid whenever possible construing one provision in a way that tends to nullify another provision, a court when confronted with such an ambiguity must consider whether the reach of the “swallowing” exclusion can be deemed narrower than its plain terms taken in isolation would otherwise suggest.
There was no dispute that a literal, plain-text reading of the catch-all provision would include BIPA violations.
The text does not seem particularly ambiguous. Quite the opposite, it seems clear as a bell- and the clear message is that the provision sweeps broadly. The text is undoubtedly broad. The Seventh Circuit agreed with Wynndalco that the catch-all provision of the exclusion is ambiguous. A plain-text reading of that provision would swallow a substantial portion of the coverage that the policy otherwise explicitly purports to provide in defining a covered “personal or advertising injury,” and arguably all of the coverage for certain categories of wrongs-copyright infringement, to take one example- that are entirely statutory in nature.
On a plain text reading, the catch-all provision has an extremely broad sweep-so broad, in fact, that the exclusion on its face would eliminate coverage for a number of statutory injuries expressly included in the definition of “personal and advertising injur[ies]” that the policy purports to cover. This clash between competing provisions of the policy gives rise to the Seventh Circuit concluding there is an ambiguity in the insurance contract language and that catch-all provision is “intractably ambiguous.”
Applying yet another well-established canon the ambiguity must be construed against Citizens and in favor of the insured. As the catch-all provision says nothing about injuries arising from statutes regulating privacy interests, and “[o]ral or written publication, in any manner, of material that violates a person’s right of privacy” is covered the Seventh Circuit concluded that the injuries alleged complaints at least potentially fall within the coverage of the Citizens policy. The Seventh Circuit concluded that Citizens thus owes its insured, Wynndalco, a duty to defend it against those complaints.
ZALMA OPINION
Exclusions in policies exist to limit the coverages provided by the insuring agreement and cause it to provide less coverage than an unlimited insuring agreement. Since people are entitled to enter into any contract that the insurer is willing to offer and the insured is willing to accept, the court will usually not rewrite the contract. There was no question that the “catch-all” exclusion was clear and unambiguous but the District Court and the Seventh Circuit created an ambiguity because the exclusion limited the effect of the insuring agreements. In this case the Seventh Circuit rewrote the policy and provided the insured more coverage than was provided by the policy.
(c) 2023 Barry Zalma & ClaimSchool, Inc.
Please tell your friends and colleagues about this blog and the videos and let them subscribe to the blog and the videos.
Subscribe and receive videos limited to subscribers of Excellence in Claims Handling at locals.com https://zalmaoninsurance.locals.com/subscribe.
Consider subscribing to my publications at substack at https://barryzalma.substack.com/publish/post/107007808
Go to Newsbreak.com https://www.newsbreak.com/@c/1653419?s=01
Barry Zalma, Esq., CFE, is available at http://www.zalma.com and [email protected]
Follow me on LinkedIn: www.linkedin.com/comm/mynetwork/discovery-see-all?usecase=PEOPLE_FOLLOWS&followMember=barry-zalma-esq-cfe-a6b5257
Write to Mr. Zalma at [email protected]; http://www.zalma.com; http://zalma.com/blog; daily articles are published at https://zalma.substack.com. Go to the podcast Zalma On Insurance at https://podcasters.spotify.com/pod/show/barry-zalma/support; Follow Mr. Zalma on Twitter at https://twitter.com/bzalma; Go to Barry Zalma videos at Rumble.com at https://rumble.com/c/c-262921; Go to Barry Zalma on YouTube- https://www.youtube.com/channel/UCysiZklEtxZsSF9DfC0Expg; https://creators.newsbreak.com/home/content/post; Go to the Insurance Claims Library – https://zalma.com/blog/insurance-claims-library.
Please tell your friends and colleagues about this blog and the videos and let them subscribe to the blog and the videos.
Subscribe and receive videos limited to subscribers of Excellence in Claims Handling at locals.com https://lnkd.in/gfFKUaTf.
Consider subscribing to my publications at substack at https://lnkd.in/gcZKhG6g
Go to Newsbreak.com https://lnkd.in/g8azKc34
Follow me on LinkedIn: https://lnkd.in/guWk7gfM
Go to Barry Zalma videos at Rumble.com at https://lnkd.in/gV9QJYH; Go to Barry Zalma on YouTube- https://lnkd.in/g2hGv88; https://lnkd.in/gYqJ_JcC, go to the Insurance Claims Library – https://lnkd.in/gWVSBde.

Insurance Expert May Not Testify to Speculative and Contains Unsupported Conclusions.
Posted on September 18, 2026 by Barry Zalma
See the full video at and at https://rumble.com/v7fmifw-expert-may-only-testify-to-what-experience-supports.html
In Michele A. Over, and The Estate Of Paul R. Over v. State Farm Mutual Automobile Insurance Company, and State Farm Fire And Casualty Company, Civil Action No. 23-cv-02243-PAB-STV, United States District Court, D. Colorado (September 14, 2026) Michele and Paul Over sued State Farm Fire and State Farm Auto over hail-damage and stolen-vehicle claims.
The operative dispute concerned State Farm Auto’s motion to exclude or limit opinions from plaintiffs’ insurance-industry expert, Aaron Castillo. Castillo.
Law
The proponent of expert testimony must establish by a preponderance of the evidence that an expert is qualified and that the opinions are helpful, sufficiently grounded, and reliably derived and applied. Experience-based opinions must explain how the...
150 Months in Prison for Tax Fraud
Post 4846
Posted on September 17, 2026 by Barry Zalma
See the full video at https://lnkd.in/g8rh3JBX and https://lnkd.in/gmkdy-9C, In United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
In United States Of America v. Thomas Addaquay, United States Of America v. Thomas Addaquay, Nos. 25-10609, 25-10611, United States Court of Appeals, Eleventh Circuit (September 9, 2026) the Eleventh Circuit affirmed all challenged convictions, the 150-month aggregate sentence, and the challenged $4,123,474.55 restitution award.
FACTS
Thomas Addaquay controlled United Consolidated Accounting and Business Services (UC), nominally a check-cashing business.
The government proved a three-stage tax-refund scheme that converted the resulting refund checks into usable funds through ...
Major Fraud Perpetrator Asserts Fifth Amendment Privilege to Avoid Prosecution
Post 5489
Posted on September 14, 2026 by Barry Zalma
Fraudster Refuses to Answer Questions About His Alleged Fraud
See the full video at https://lnkd.in/gvicAMDr and at https://lnkd.in/gvicAMDr
In Great American Insurance Co. v. Gemstone Property Management, LLC, et al., No. 23-cv-9100 (LJL), United States District Court, S.D. New York (September 8, 2026) Great American Insurance Company alleged that it was defrauded through a scheme in which Subin Associates, LLP recruited individuals to stage construction-site injuries, arranged unnecessary medical treatment and litigation funding, and pursued fraudulent personal-injury claims.
Luis Manuel Garcia Salcedo, resulted in a $6 million settlement. Non-party Jose Hernandez allegedly worked as an assistant manager at Subin, operated Hernandez Associates, and owned litigation-funding companies that shared office space with Subin and provided services to its clients.
After Great American ...
Alleged Defamatory Statements Must be Of and Concerning Plaintiffs
Posted on October 16, 2026 by Barry Zalma
To Prove Defamation the Statement Must be Of and Concerning the Plaintiffs
Post 4867
In Michael Moloney and Sergio Cantu v. United Services Automobile Association, No. 04-25-00519-CV, Court of Appeals of Texas, Fourth District, San Antonio (October 14, 2026) Michael Moloney and Sergio Cantu appealed from the trial court’s granting of a traditional motion for summary judgment in favor of United Services Automobile Association (“USAA”) on their defamation claim.
BACKGROUND
Moloney and Cantu sued USAA for defamation, alleging that they are the principals of Informed Roofing & Restoration, LLC (“Informed Roofing”), which is primarily engaged in the residential roofing repair and replacement business, and that an employee or agent of USAA had made false and defamatory statements to the San Antonio Police Department (“SAPD”) concerning them.
Specifically, Moloney and Cantu alleged that an employee of ...
ZIFL – Volume 30, Issue 20 Subscribe to ZIFL here https://lnkd.in/gfpn78FM
Posted on October 15, 2026 by Barry Zalma
THE SOURCE FOR THE INSURANCE FRAUD PROFESSIONAL
Zalma’s Insurance Fraud Letter (ZIFL) continues its 30th year of publication dedicated to those involved in reducing the effect of insurance fraud.
ZIFL is published 24 times a year is written by Barry Zalma.
It is provided FREE to anyone who visits the site at https://lnkd.in/gVT5G9s
Six Insane Fraud Schemes the Trump Administration Has Uncovered Stealing from the taxpayer has now become a multi-billion-dollar industry in America. Obamacare has been a magnet for scammers.
Florida Insurance Agent Pleads Guilty in $300,000 Premium Finance Scheme
Daniel Raney, 41, who managed Raney Insurance and Raney Ventures in Pensacola, was arrested after AFCO Direct.
RIFE WITH FRAUD ALLOWS DEMANDS TO ESTABLISH RESTITUTION
Six Insane Fraud Schemes the Trump Administration Has Uncovered
Stealing from the taxpayer has now become a multi-billion-dollar industry in America – and the ...
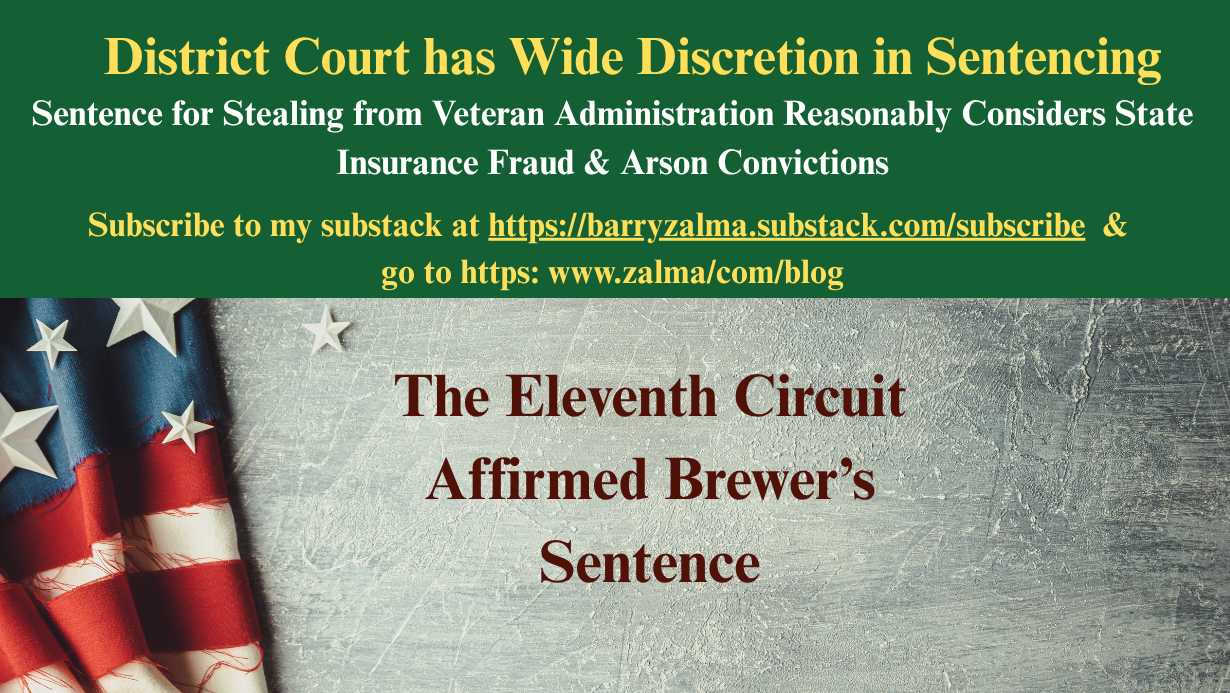
Sentence for Stealing from Veterans Administration Reasonably Considers State Insurance Fraud & Arson Convictions
Post 4863
Posted on October 14, 2026 by Barry Zalma
In United States Of America v. Anthony Curtis Brewer, No. 26-10745, United States Court of Appeals, Eleventh Circuit (October 8, 2026) Anthony Curtis Brewer became the fiduciary for an incapacitated recipient of Department of Veterans Affairs survivor benefits and agreed to use her funds solely for her care and support without commingling them with his own.
The VA determined that he misused $67,232.33 and removed him as fiduciary in 2022. Brewer pleaded guilty to theft of more than $1,000 in government property under 18 U.S.C. § 641. At sentencing, the district court attributed $53,567 in loss to him, producing an advisory Guidelines range of 15 to 21 months.
Citing the victim’s vulnerability, Brewer’s attempts to avoid responsibility, and his other fraudulent conduct — including state convictions for arson and insurance fraud — the court ...